Claim: winnings will arrive in the same app
Do not treat the payment interface as a general receiving balance for casino winnings. Ask the operator to name the actual outbound destination and payment service. It may offer a supported debit-card payout or a transfer to your verified bank account, but those arrangements must be confirmed for your account rather than inferred from the deposit experience.
An app displaying the card used for payment does not mean it holds the deposited money or controls the casino balance. The operator’s withdrawal cashier and terms are the relevant sources for money out. If support answers with instructions for making a deposit, repeat the question explicitly: how are winnings paid to me?
| What is visible | What it establishes | What remains unproven |
|---|---|---|
| Payment button | A checkout option is presented | Withdrawal availability |
| Successful authentication | A funding instruction was authorised | Eligibility for an outbound credit |
| Card listed in the app | A card is associated with the service | That this card can receive the casino payout |
Claim: different last digits mean the wrong card was used
Tokenisation can mean that the identifier recorded for a mobile payment differs from the physical card number. That difference alone does not establish a mistake or an unauthorised transaction. Ask which masked identifier the operator needs to match the original funding record, using the official wallet and issuer guidance to locate it.
If a card was replaced after the deposit, explain both events: the tokenised funding and the replacement. Removing a card from an app should not be assumed either to cancel an existing payout or to redirect it. The operator and issuer need to clarify what the actual outward instruction will use.
Keep screenshots tightly cropped and avoid including unrelated transactions. Ownership evidence should answer the specific verification question, not expose the rest of your financial activity unnecessarily.
Claim: a quick deposit predicts a quick withdrawal
Deposit authorisation, operator review and outward settlement are different processes. Fast authentication at checkout says little about how soon the payments team will approve a withdrawal. A payout estimate needs a starting point and an endpoint: request received, review finished, external submission or funds credited. Without those definitions, two short-looking claims may describe different portions of the journey.
- Read the selected withdrawal route’s processing description while signed in.
- Ask whether review is included and whether the estimate uses calendar or business days.
- Confirm the receiving card or bank account and any route-specific eligibility.
- Save the request reference and compare progress against the terms that actually apply.
A service may be technically available outside office hours while the operator’s review team follows another schedule. Customer chat being open does not settle that distinction. Nor does a weekend delay establish that the app or card issuer is responsible; first find out whether any payment has been released.
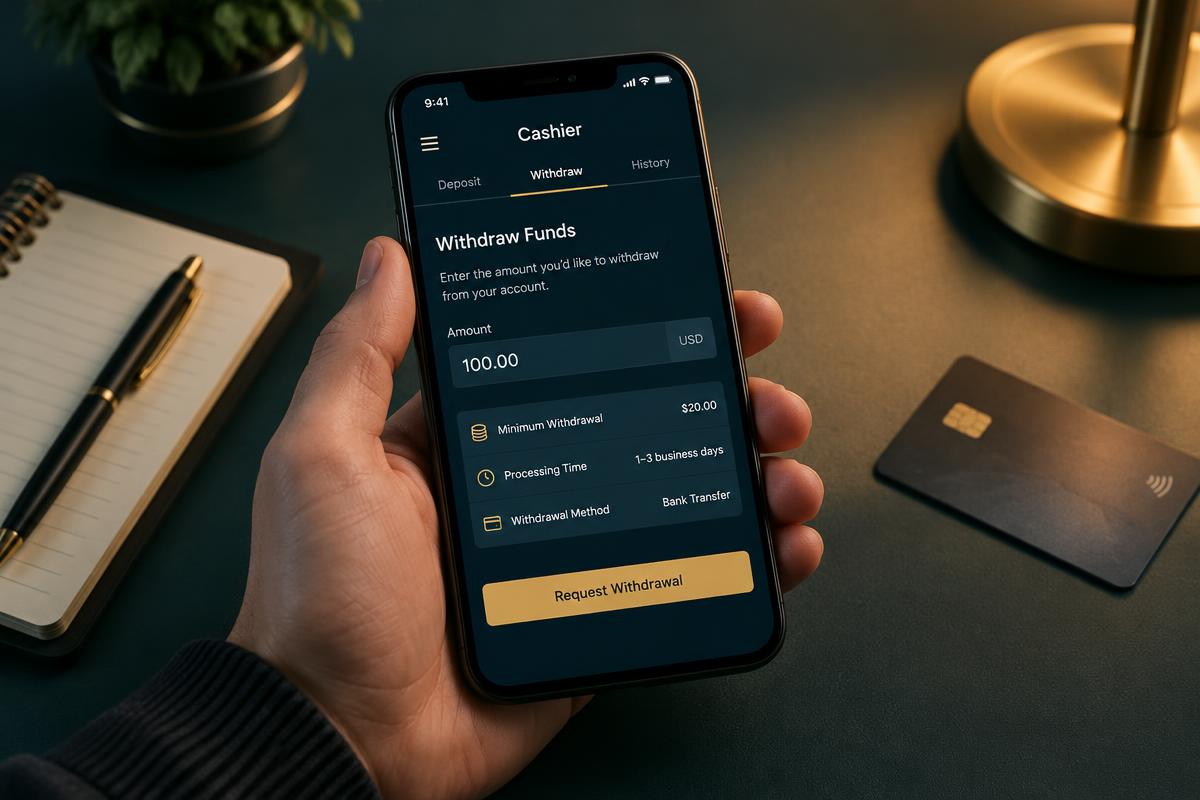
Claim: the checkout provider can release a pending casino withdrawal
A pending balance inside the casino generally needs an explanation from the operator. The checkout provider cannot be assumed to control that internal review. Ask whether the hold-up concerns identity, payment ownership, balance conditions or submission. Directing the enquiry to the party that can take the next action is more useful than contacting every organisation at once.
If the operator says funds have left, obtain the actual outward route, masked destination and traceable reference. A card issuer can investigate a card credit; a receiving bank can examine a bank transfer. Those are more precise enquiries than asking where a supposed app withdrawal has gone.
When ordinary support gives no substantive answer, use the operator’s formal complaints process. Preserve the original request and status changes. For eligible unresolved gambling disputes, its named alternative dispute resolution service becomes available after eight weeks or an earlier deadlock response. Keep any separate card or banking complaint focused on that institution’s own handling.
Claim: the underlying funding source no longer matters
UK-licensed gambling businesses cannot accept credit-card gambling payments. A mobile payment interface does not make an otherwise prohibited funding source acceptable. Use a supported debit arrangement and do not attempt to conceal the source through a different checkout. The operator may also need to establish ownership of the card behind a tokenised transaction.
Age and identity checks should occur before gambling. A later request can still be justified, including where legal duties or new circumstances require it, but an operator should not save reasonably available checks for withdrawal time. Ask what evidence is needed, why it is needed now and how to provide it securely.
Funding history can also affect which outward destination the operator permits. Ask about an approved alternative if the original card is closed or cannot receive the payment. The debit-card guide is useful where that is an existing site route, but the important point remains the same: the specific outward service must be confirmed.
Keep the convenience without adding assumptions
Advantages
- Tokenised checkout can reduce the need to type card details repeatedly.
- An existing card may make the funding record easier for you to recognise.
Limitations
- The checkout experience does not describe how winnings are delivered.
- Token and replacement-card details can require careful record matching.
Before choosing an offer, separate payment convenience from promotional restrictions. UK bonus wagering requirements are capped at 10 times the bonus funds. Read the actual conditions and the effect of cancelling a promotion; a smooth deposit experience does not make restricted promotional funds immediately withdrawable.
Check charges, currency and the cashier’s actual limits rather than adopting a universal minimum from a generic guide. If a small balance cannot be requested, ask about its permitted return instead of adding funds. Keep money marked for withdrawal out of further play, and leave any gambling blocks or spending controls in place while the payment is resolved.
Frequently asked questions
Where should I look for the real withdrawal method?
Do unfamiliar masked digits prove a payment problem?
Should I remove and re-add my card to speed things up?
Problems players reported, and how to avoid them
These are attributed player reports, not findings against the operators. Each links to its source and a practical next step when a withdrawal is delayed.
xxshepxx, historical AskGamblers case: The player alleged a claimed 50% match was never credited and a £170 withdrawal was refused because of that bonus, although support disputed the claim. Historical case; not evidence of current performance. AskGamblers labels case Unsolved; historical case, not current performance evidence.
Val, Trustpilot, 29 May 2025: Val alleged deposits worked but the account was blocked when attempting to withdraw. No resolution visible in retrieved review.
sponge2025, AskGamblers forum, 28 May 2026: The poster alleged that after a £300 bank withdrawal and a further £200 request, Betfred closed the account and support said funds would be retained under safer-gambling policies. Unresolved in retrieved initial post.
Sophie Langford’s editorial remit covers UK casino cash-outs, payment ownership and the journey from an accepted request to spendable funds. The guides prioritise clear conditions, useful comparisons and practical answers when a payment stalls.